
Polysilicon Import Rules Complicate Pre-Tariff Inventory Planning
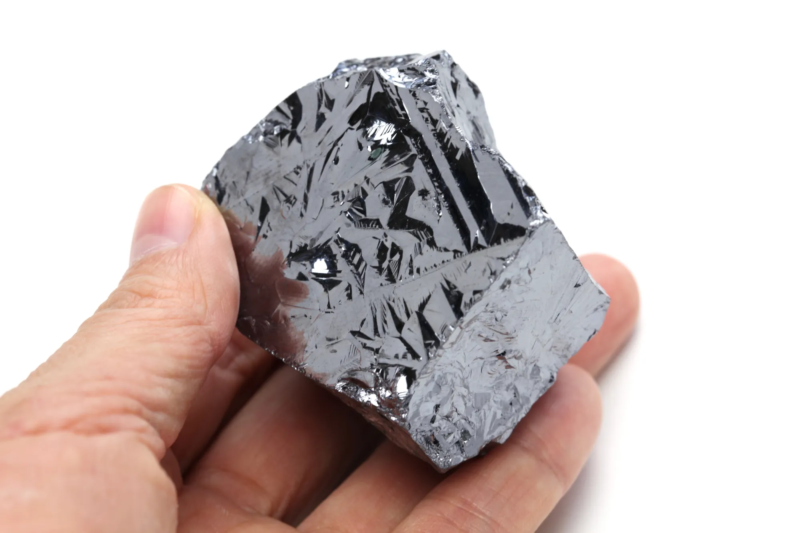 The traditional strategy of increasing imports before a tariff takes effect has become more complicated for companies purchasing polysilicon and covered derivatives in the United States. A new Commerce Department rule, effective September 22 through December 3, gives the government authority to restrict additional imports when company volumes indicate that material is being stockpiled ahead of the December 4 implementation of new Section 232 measures.
The development is significant because the government is not simply changing the cost of imported polysilicon. It is actively monitoring purchasing behavior during the period before the new measures take effect.
How the New Restrictions Work
Commerce is comparing current import activity with historical volumes to identify companies whose purchases are substantially above their normal levels. Existing importers identified as stockpiling can be prohibited from making additional entries before December 4, although the rule provides a waiver process.
Companies that became new importers of record after August 6 face specific weekly limits unless Commerce approves a waiver. The limits vary by covered HTSUS classification and include quantities as low as 7 kilograms for certain polysilicon derivative classifications.
The rule also directs customs brokers to consider ownership, import behavior, and the ultimate consignee when evaluating new importers. Commerce has specifically stated that arrangements designed to circumvent the restrictions can result in enforcement action.
This makes importer history, product classification, ownership structure, and intended use important considerations for companies planning purchases before December 4.
What Changes on December 4
The restrictions are designed to bridge the period before a broader Section 232 regime takes effect.
Beginning December 4, covered polysilicon will be subject to minimum import prices, including $21 per kilogram for polysilicon and $100 per kilogram for polysilicon ingots and wafers. Certain covered derivatives will also face an additional 15% tariff, subject to country-specific provisions and other requirements.
The policy is intended to create a more commercially viable environment for U.S. polysilicon production while reducing dependence on foreign supply. The administration has also authorized incentives for companies that establish or expand domestic polysilicon, ingot, wafer, and cell production.
For buyers, however, the immediate issue is the transition period between today’s import environment and the new December requirements.
Why Classification and Import History Matter
The new framework creates a distinction between buying inventory for legitimate commercial demand and increasing imports primarily to avoid future pricing measures.
That distinction requires companies to examine their specific circumstances rather than assuming that additional pre-tariff inventory can be imported without restriction. HTSUS classification, importer-of-record history, historical purchasing volumes, country of origin, supplier contracts, intended use, and documentation can all affect how an import is treated.
The rule also makes clear that the restrictions apply specifically to polysilicon products and covered derivatives. It does not establish a blanket restriction on semiconductor inventory.
That distinction is important for OEMs and EMS providers whose concern is the potential downstream effect on semiconductor and electronics costs.
Potential Effects Further Down the Supply Chain
Polysilicon sits at the beginning of the semiconductor manufacturing chain. The August Section 232 proclamation identifies it as the base material for semiconductor production and links domestic polysilicon availability to U.S. semiconductor manufacturing capacity.
Higher polysilicon and wafer costs could therefore influence downstream pricing, although the effect will vary considerably by product, supplier, contract structure, classification, and the amount of polysilicon exposure embedded in the finished component.
It would be premature to assume that the policy will create shortages across semiconductor markets. The more immediate concern is increased cost and uncertainty around specific supply chains exposed to covered materials.
Where Inventory Strategy Still Applies
The new restrictions also illustrate why inventory strategy needs to distinguish between upstream raw materials and finished, production-qualified components.
For companies with confirmed requirements, securing qualified semiconductors, assemblies, modules, or other finished products through authorized channels can provide a way to manage potential downstream cost increases without attempting to stockpile restricted polysilicon itself. An inventory ownership structure can fund and hold that physical inventory, preserve it under controlled conditions, and schedule releases against documented production requirements.
That approach does not bypass the Commerce restrictions or eliminate the need for accurate classification and import compliance. Where covered polysilicon products are involved, any purchase should be based on legitimate commercial demand, appropriate documentation, and any required Commerce approval.
Planning Through the December Transition
The period between September 22 and December 3 creates an unusual procurement environment. Companies are preparing for higher minimum import prices and additional duties while Commerce is simultaneously monitoring whether current import activity represents stockpiling.
For OEMs and EMS providers, the most important consideration is understanding exactly where polysilicon exposure exists within the supply chain. That means identifying affected classifications, reviewing supplier contracts, assessing potential downstream cost exposure, and separating legitimate production requirements from speculative inventory accumulation.
The new rule does not eliminate the value of inventory planning. It makes the distinction between compliant supply assurance and restricted stockpiling much more important.